Can you get approved for a car loan with bad credit?
If a lender has already told you no, the real question is not whether approval is possible. It is what has to line up for it to happen. Drivers across Kansas City finance vehicles every month with credit a bank would call thin, damaged, or both. What changes the outcome is knowing what sits behind the decision and walking in with the right paperwork in hand.
What a lender is actually weighing
A credit score compresses years of history into three digits, and plenty gets lost on the way. Underneath the number, the questions are simpler than most people expect:
- Is your income steady, verifiable, and large enough after your existing obligations?
- How long have you lived at your current address, and can you document it?
- What is your track record specifically on auto loans, which lenders read differently from credit cards?
- How much are you putting down, and does the vehicle price fit the income?
Timing matters as much as severity. A repossession from four years ago carries less weight than a missed payment from last month, and a medical collection reads very differently from a charged off car loan. Two applicants with identical scores can get two very different answers.
Why a low score is not an automatic no
Banks and credit unions buy loans in volume, so they set score cutoffs to keep underwriting fast and uniform. A dealership that finances in house does not have to work that way. At The Big Lot Car Credit the decision gets made here on Prospect Avenue, against your whole situation, so a score in the 500s starts a conversation instead of ending one. Stable income and a workable down payment routinely move the needle further than the number itself.
What to bring so a decision can happen in one visit
Most delays come down to missing documents rather than credit. Gather these before you come in:
- A current, valid driver's license
- Proof of residence, such as a utility bill or piece of mail dated within the last 30 days
- Proof of income: your two most recent pay stubs, a Social Security award letter, or pension documentation
- Names, addresses, and phone numbers for 10 local references
The reference list catches people off guard, but it is standard for in house financing. Putting it together at your kitchen table is far easier than assembling it from memory at the desk.
Two levers you control
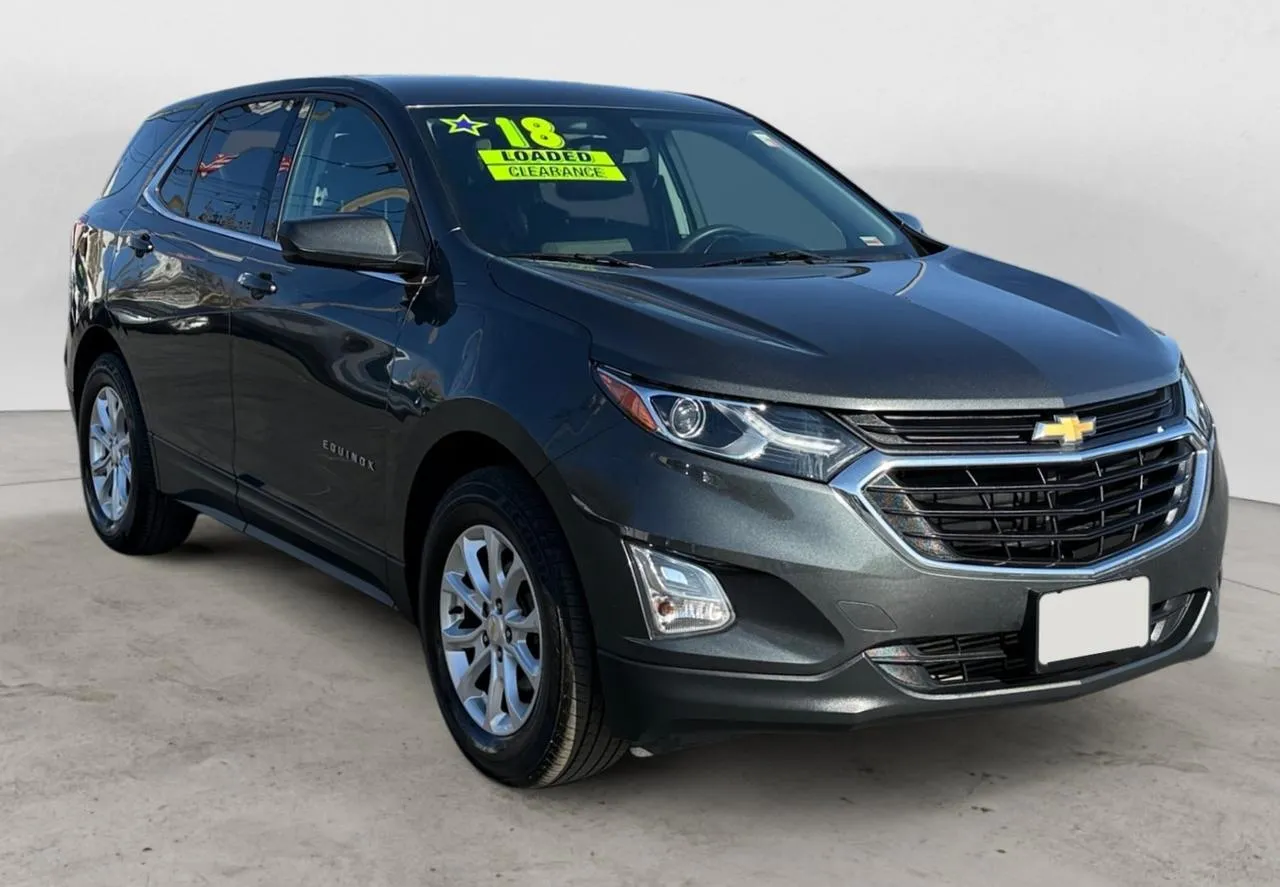
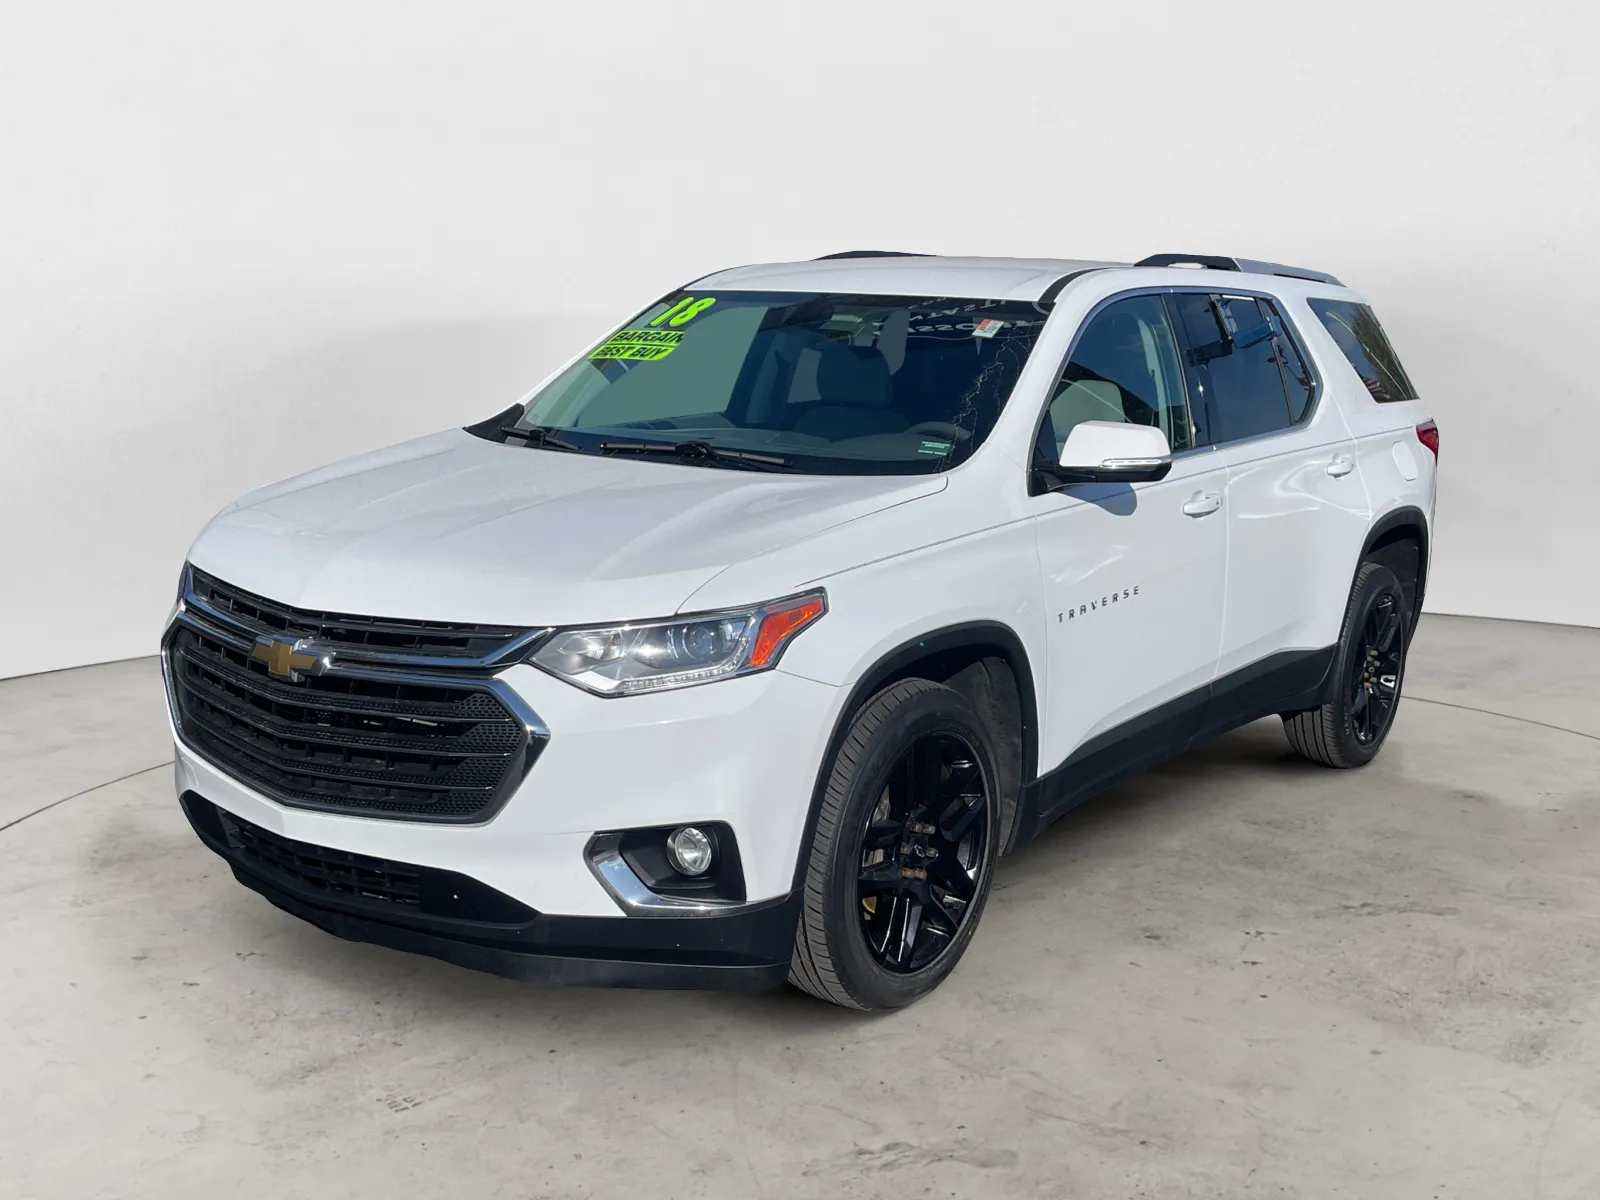
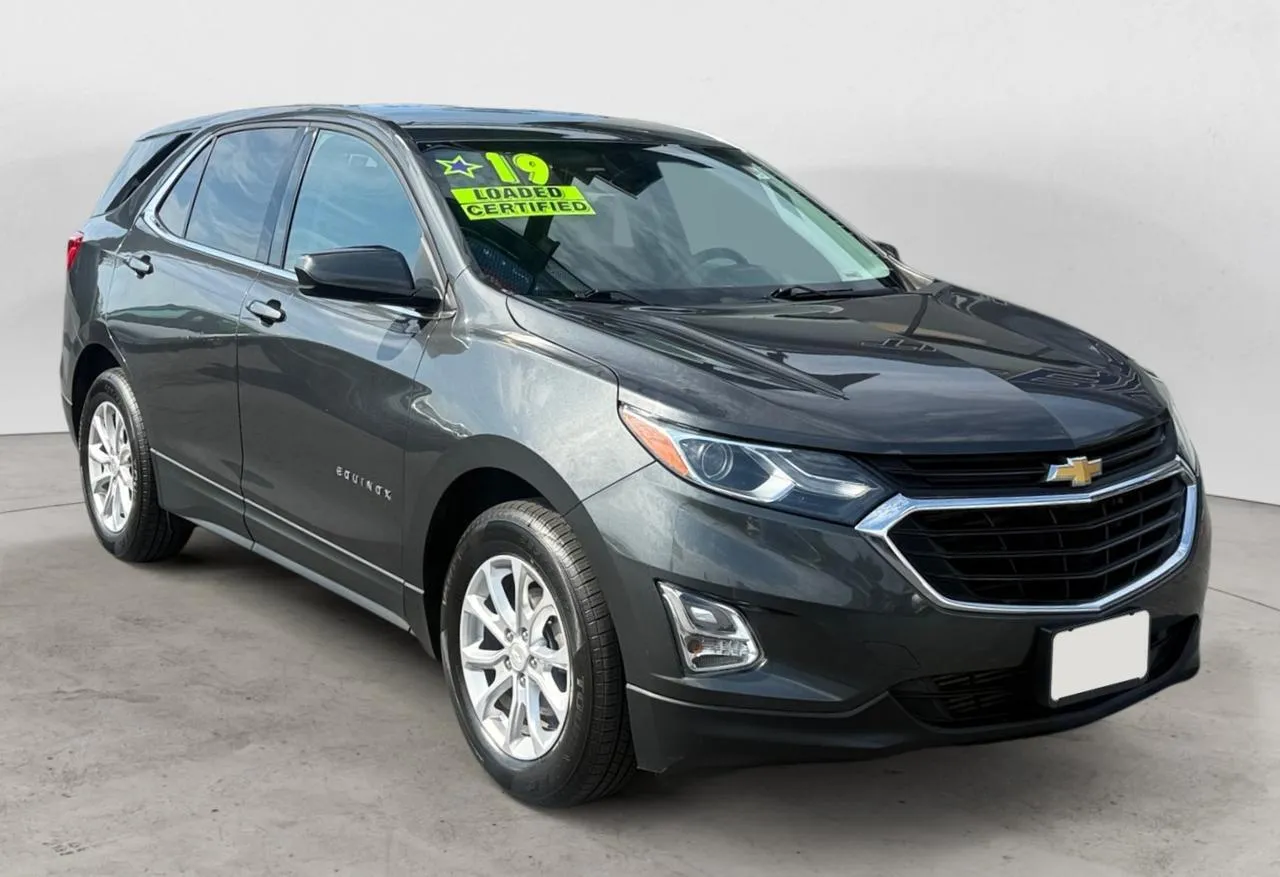
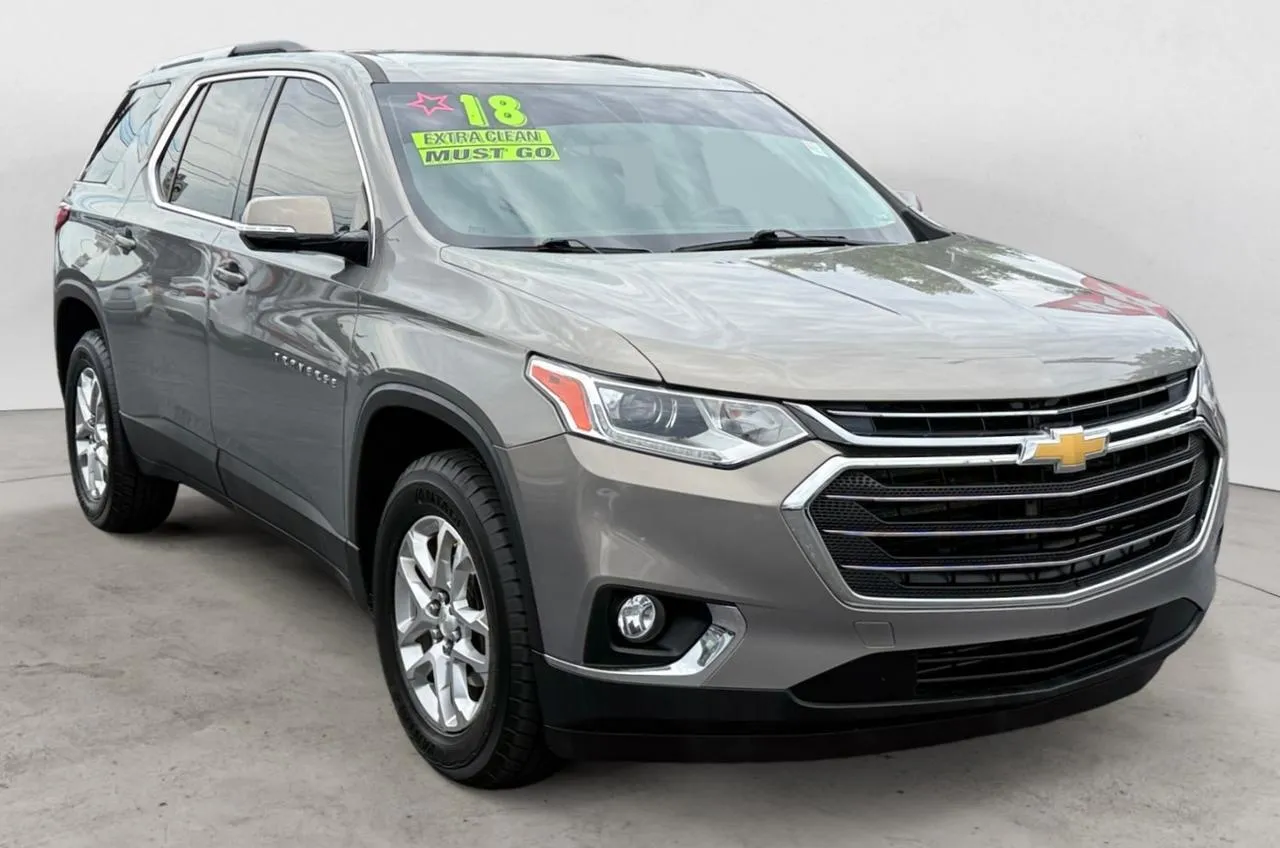
The first is the down payment. More money down shrinks the amount financed, shortens the term, and makes an approval easier to write. The second is the vehicle itself. Reaching for something at the very top of your budget puts pressure on the application, while a reliable crossover a couple thousand under your ceiling often turns a maybe into a yes.
Run a few combinations through our payment calculator before you shop so you know which price range actually fits your paycheck.
Approval is the start, not the finish
Financing with damaged credit only helps if the loan works for you afterward. Ask whether payments get reported to a credit bureau, what coverage comes with the vehicle, and what happens if a payday lands after a due date.
Start from where you are
You do not have to repair your credit before you shop. You need a realistic budget, your documents together, and a dealership that reads the full file. Browse the current inventory, start your financing application, or call (816) 241-5100 and we will tell you plainly where you stand.